Home Loan Rules & Eligibility in 2026 The Real Factors Banks Check
If you have ever spent time checking your home loan eligibility online, you have probably simply added the details, click a button, and found yourself eligible for the huge amount.
- What Has Changed in Home Loan Rules in 2026?
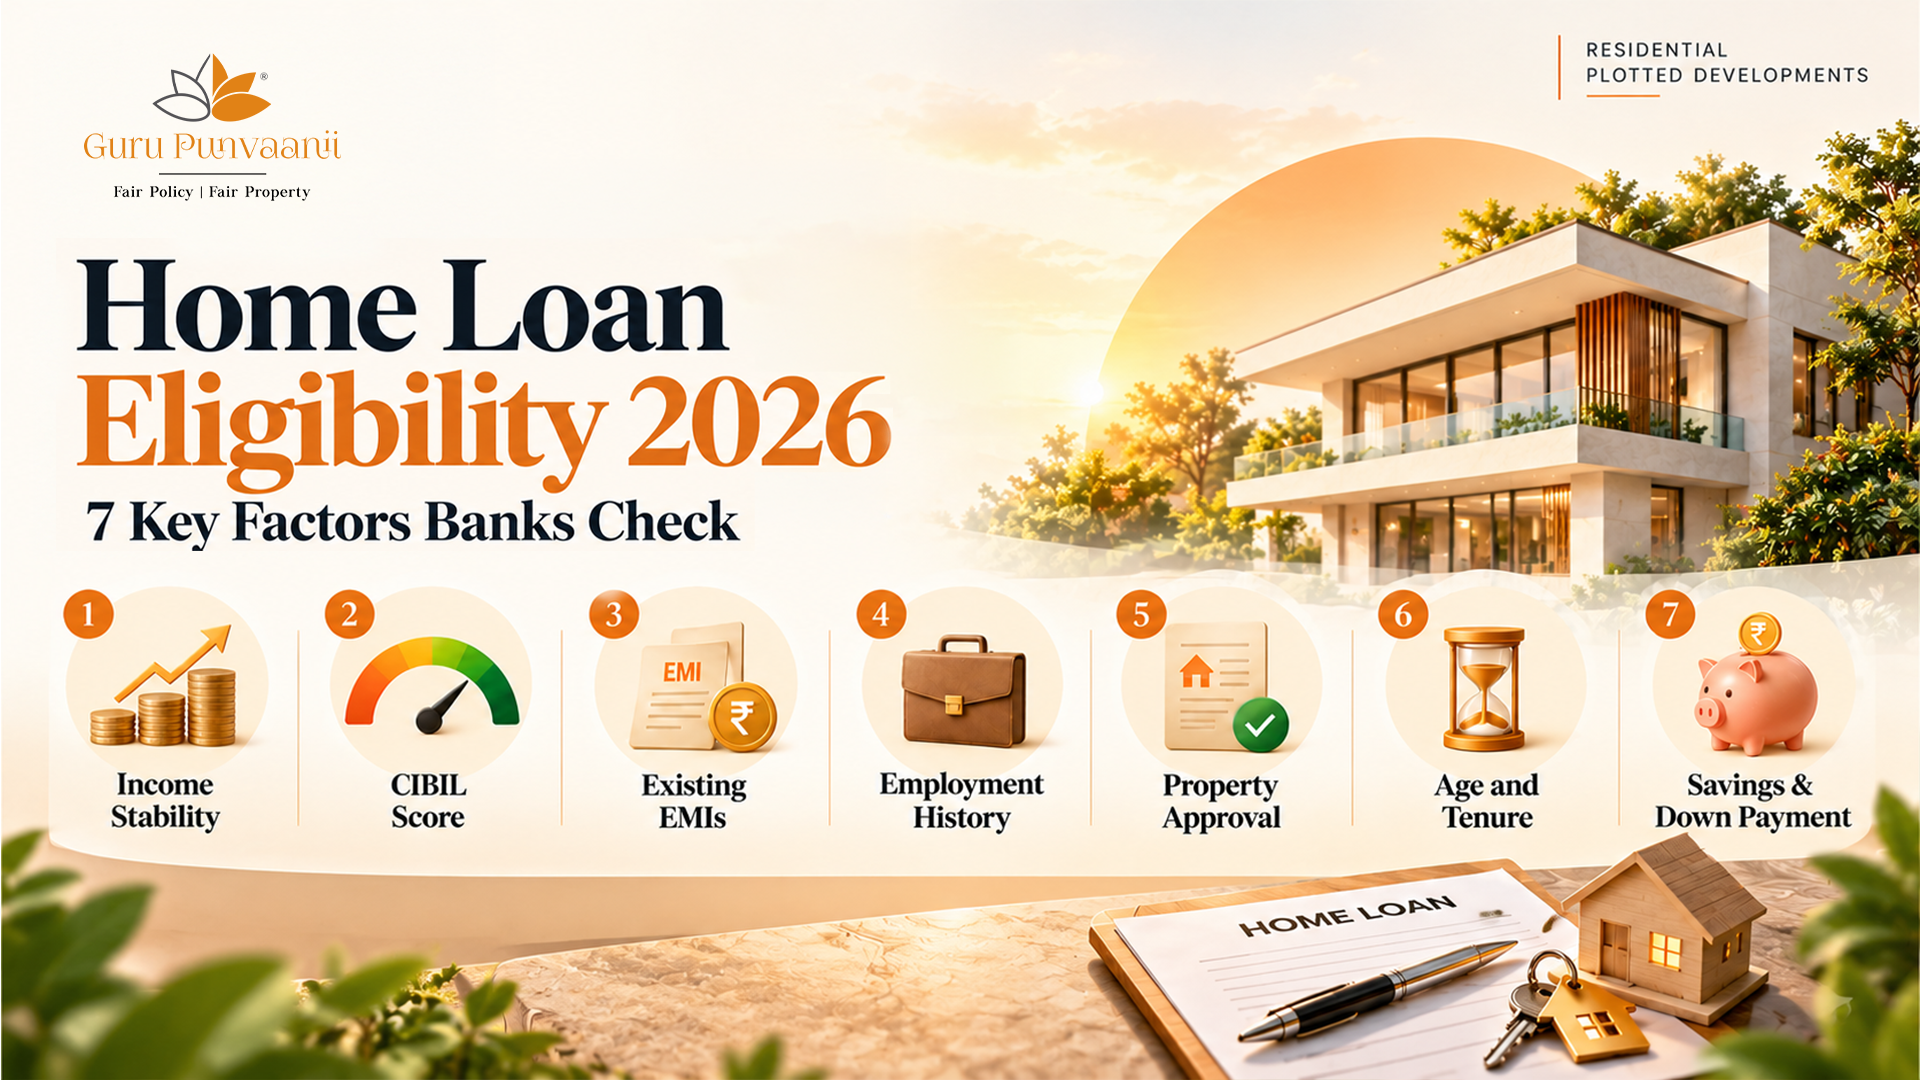
- The 7 Real Factors Banks Check Before Approving Your Loan
- 1. Income stability
- 2. Credit Score & Repayment History
- 3. Existing Loans & EMI Burden
- 4. Employment Type & Work History
- 5. Property Type & Approval Status
- 6. Age & Loan Tenure
- 7. Savings, Down Payment & Financial Discipline
- How Much CIBIL Score Is Required for a Home Loan in 2026?
- Home Loan Eligibility for Self-Employed in 2026: What’s Different?
- Final Thoughts
- Frequently Asked Questions
Well, reality is a bit different! When you can actually visit the bank and get into the process of getting a home loan approved, things feel way different than you imagined. That is because banks do not work on calculators but on patterns, risks, and behavior. And in 2026, home loan rules have become much more data-driven and honestly, a little stricter.
So, in this guide, we will help you understand what exactly these banks are looking for, and how you can also be in the good books. This way, you can realistically improve your chances and perhaps buy yourself a dream home without worries.
Without any further ado, let’s get into it!
What Has Changed in Home Loan Rules in 2026?
You cannot understand the bank’s reasonings, without understanding what exactly has changed over the years. There has been the biggest shift in home loan rules in 2026, and that is that banks now care less about what you say you earn, and more about how you manage your money.
- Now, there is a deeper digital verification, which includes digging and scanning your bank statements, UPI patterns, and spending habits.
- They prefer you to have a stable income of ₹50K as your salary, than an inconsistent ₹1L for one month, and ₹10k next.
- When it comes to home loan for self-employed eligibility, lenders now want clear proof of long-term income.
- It’s not just about how much CIBIL score is required for a home loan, but how you maintain it.
So yes, in 2026, eligibility is not just about a snapshot of numbers, but your financial story over time.
The 7 Real Factors Banks Check Before Approving Your Loan
1. Income stability
Alot of self-employed people think their amount spikes in the account means the banks will start trusting them more and more. And while that can be true till a point, banks are not just impressed by high numbers if they keep fluctuating. If you are salaried, then that suggests consistency. Being self-employed but having a regular flow of income will always matter more than sudden big spikes. And here is a thing, for home loan for self-employed eligibility, even one unstable year in your ITR can raise concerns.
2. Credit Score & Repayment History
This is probably the most common and talked factor in question: how much CIBIL score is required for a home loan? Let us make it easy for you to understand:
| CIBIL Score | What It Means |
| 750+ | Strong approval chances |
| 700–750 | Decent |
| 650–700 | Risk zone |
| Below 650 | Likely rejection |
However, that is not all. In fact, a lot of you miss that banks out there are also keeping a strict check upon your missed EMIs, Credit card overuse, and loan closures. So yes, how much CIBIL score required for home loan matters, but your financial behavior and patterns aren’t any less valuable for them!
3. Existing Loans & EMI Burden
Talking of loans, let’s dig a little deeper into this. Banks usually calculate something called FOIR which stands for Fixed Obligation to Income Ratio. It simply asks about how much of your income is already committed to EMIs. If you have too many EMIs, then that would suggest lower eligibility, no matter what the home loan rules might say!
4. Employment Type & Work History
Another thing that can make or break your chances for a home loan is your job! For example, if you are someone who has changed too many jobs in too little time, it can mean that you are financially unstable as per their home loan rules. Also, if you are less than 2 years into a job, it is not a definite rejection but can be something to consider for them. Which is why, when it comes to business owners, home loans for self-employed eligibility depend heavily on the years they have spent in the business and how stable the industry is.
5. Property Type & Approval Status
Now comes the point where a lot of customers while going through real estate projects do not pay enough attention to! Banks are all about trust and transparency when it comes to loans. If the home you are picking is from a developer that does not have a good record, you are likely going to face rejection. Which is why, if you read about us, you will know about our RERA-approved properties, clear land titles, and what makes us one of the trusted developers in Bangalore. At our end, we focus on legally clear and well-structured developments because your property can directly affect your loan approval and future.
6. Age & Loan Tenure
You might not expect this, but your age can play a big role in home loan eligibility. It is mainly because it affects how long you have to repay the amount you take! Basically, the banks prefer to go for those who have a longer repayment window. So, if you are young, then you have an advantage already which increases your eligibility. On the other hand, if you are applying later in your career, the repayment window naturally shrinks. And well, banks typically want the loan to be paid before retirement, so they end up offering higher EMIs for short tenures and reduce the amount!
7. Savings, Down Payment & Financial Discipline
Last but not least, banks are never just checking one thing or the else to approve your loan. They are looking for those who fit best with their home loan rules and show predictability and transparency in the process. So, besides just your CIBIL score, they are also looking at your bank balance patterns, whether you save regularly, and how you manage your expenses.
How Much CIBIL Score Is Required for a Home Loan in 2026?
In 2026, there are banks who still use CIBIL score as a key eligibility factor, while as we discussed, it cannot be the only factor they consider.
In real cases, a person with a 720 score and a clean repayment history can get approved faster than someone with a 780 score, but irregular payments or high credit usage. This is because banks have not also started to focus on your behavior consistency than just a number.
So, if you want to improve your chances under the current home loan rules, here is what we would suggest you:
- Pay your credit card bills on time
- Avoid taking multiple active loans at once
- Keep your credit utilization below 30-40%
Home Loan Eligibility for Self-Employed in 2026: What’s Different?
This is a part which creates the most confusion, and it is also where banks can get really strict! If you are self-employed, your income can fluctuate, which is not very ideal for banks. So, home loan for self-employed eligibility now depends heavily on:
- 2-3 years of ITR
- GST filings
- Business continuity
- Bank statement consistency
| Factor | Salaried | Self-Employed |
| Income Proof | Salary slips | ITR + GST |
| Stability Check | Job history | Business continuity |
| Approval Speed | Faster | Slower |
| Risk Perception | Lower | Higher |
Final Thoughts
From this guide, one thing has become clear when it comes to real estate: your loan does not depend on you, as it depends on what you are buying.
You need to be mindful, as now the banks are getting stricter and are more comfortable with lending legally approved projects, transparent documentation, and trusted developers. This is why our focus is on bringing you RERA approved, legally clear properties that are built with long-term value in mind.
If you are looking for our residential or industrial projects, you can connect with us and we can guide you through the home loan rules, so banks do not feel like a hassle.
Frequently Asked Questions
1. What is the minimum down payment required for a home loan?
Usually, it is somewhere between 10% to 5% of the property value. If there is a higher down payment, it will definitely improve your eligibility and chances to reduce the burden of EMI.
2. Are there age limit rules for home loan eligibility?
Yes! Most banks prefer applicants between the age of 21-60. But younger applicants can get longer tenures, and that can work in your favor. So, if you are a first-time investor at Guru Punvaanii, you might actually get an advantage!
3. What is the debt-to-income ratio required for home loan approval?
Banks typically prefer your total EMIs to be below 40–50% of your monthly income.
4. How much CIBIL score is required for a home loan in 2026?
Ideally 750 or above. But beyond how much cibil score is required for a home loan, your repayment behavior plays a big role.
5. How much home loan can a self-employed person get?
It actually depends a lot on your income stability, ITR records, and consistency of the business and industry potential. If you have strong financials which show stability, then it can improve home loans for self-employed eligibility significantly.